What is the market overview of the Polyurethane (PU) Resin Market?
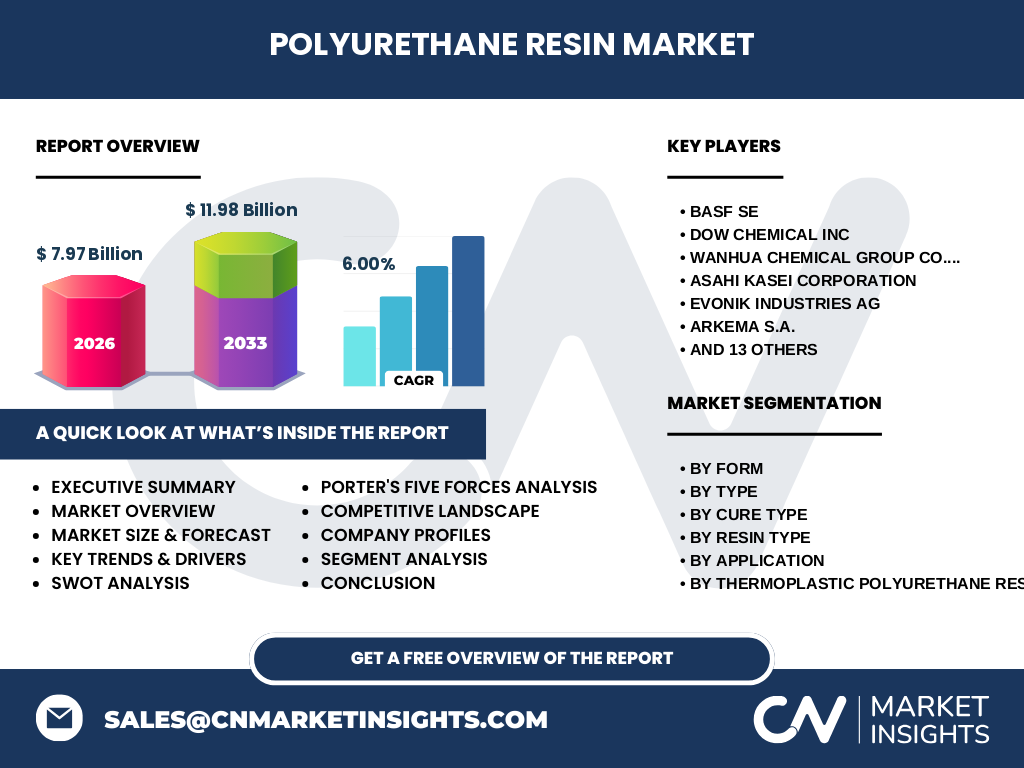
Our analysis indicates the Polyurethane (PU) Resin Market is valued at 7.97 Billion in 2026. This sector encompasses versatile polymers synthesized through diisocyanate and polyol reactions, serving vital roles in automotive, construction, and insulation. Industry significance stems from exceptional durability and thermal efficiency.
What are the key market drivers, restraints, challenges, and opportunities shaping the Polyurethane (PU) Resin Market?
Growth is propelled by surging construction demand and lightweight automotive requirements. Conversely, strict REACH environmental regulations regarding isocyanate emissions act as restraints. Raw material price volatility poses ongoing operational hurdles, while bio-based polyols present lucrative expansion opportunities.
Emerging trends and growth patterns in Polyurethane (PU) Resin Market
The sector experiences a profound pivot toward sustainability, with eco-friendly water-based and recyclable thermoplastic polyurethane resins gaining traction. Major manufacturers like BASF SE and Covestro are heavily investing in bio-feedstocks to comply with stringent European Union circular economy directives.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted global supply chains, halting automotive manufacturing and construction projects globally. However, a robust post-pandemic recovery trajectory materialized as pent-up industrial demand rebounded, accelerating adoption in pharmaceutical cold-chain packaging and healthcare infrastructure.
Competitive landscape and strategic dynamics
Market concentration remains moderate to high, dominated by multinational chemical giants possessing integrated value chains. Firms such as Dow Chemical Inc and Wanhua Chemical Group Co. Ltd. leverage massive scale, whereas specialty compounders focus on high-performance thermoplastic grades to maintain pricing power.
Executive summary of the Polyurethane (PU) Resin Market
The Polyurethane (PU) Resin Market industry trends point to robust expansion, scaling from 7.97 Billion in 2026 to 11.98 Billion by 2033 at a 6.00% CAGR. Strategic positioning hinges on green chemistry compliance and lightweighting innovations.
Market forecast from 2027 to 2033
Our forecast models steady acceleration, projecting the market to reach 11.98 Billion by 2033. Driven by a solid 6.00% CAGR from 2027 onward, expansion is underpinned by infrastructure investments across developing economies and stringent energy-saving building codes.
Segmentation analysis by form, type, cure, resin, and application
Segmentation spans multiple dimensions: Form (Liquid, Solid, Powder), Type (Thermosetting, Thermoplastic), Cure Type (Moisture, Heat, UV), Resin Type (Solvent-based, Water-based), and Application (Construction, Transportation, Pharmaceuticals, Paints and Coatings). Water-based and thermoplastic categories drive sustainable manufacturing shifts.
Regional market analysis and geographic distribution
Geographic performance highlights Asia-Pacific as the dominant manufacturing hub, anchored by rapid urbanization in China and India. North America and Europe follow closely, driven by stringent thermal insulation standards and established automotive assembly clusters requiring advanced coatings.
In-depth regional review of key markets
Asia-Pacific leads consumption due to expansive infrastructure development and automotive production out of major ports in China, South Korea, and Japan. Meanwhile, North American growth focuses heavily on energy-efficient commercial retrofits complying with EPA and Department of Energy guidelines.
Company profiles and strategic positioning
Industry leaders maintain distinct strategic moats. Huntsman Corporation and Evonik Industries AG focus on high-value specialty additives, while Arkema S.A. and Mitsui Chemicals Inc. prioritize bio-derived formulations to capture eco-conscious market share across global distribution channels.
Porter's Five Forces analysis of the industry
Supplier power is moderate due to consolidated upstream isocyanate producers. Buyer power remains high as automotive OEMs demand custom formulations at competitive price points. Threat of substitutes is mitigated by polyurethane's unmatched versatility across rigorous structural applications.
SWOT analysis of the sector
Strengths include exceptional mechanical properties and insulation value. Weaknesses involve toxicity concerns surrounding raw isocyanates. Opportunities lie in circular recycling technologies for thermoplastic grades. Threats stem from volatile petrochemical feedstocks and tightening environmental compliance mandates.
Value chain analysis from raw materials to end-users
The value chain originates with upstream petrochemical refiners supplying crude oil derivatives like benzene and toluene. Midstream chemical processors synthesize polyols and diisocyanates, subsequently formulated by resin manufacturers into liquid or solid systems for downstream industrial convertors.
Investment insights and strategic recommendations
Investors should target greenfield expansions in water-based and recyclable thermoplastic polyurethane resins. Partnerships with regional distribution networks in emerging markets offer high-yield entry points, bypassing logistical hurdles associated with hazardous chemical transport.
Conclusion and key takeaways
The Polyurethane (PU) Resin Market analysis confirms a healthy growth trajectory reaching 11.98 Billion by 2033. Success requires proactive adaptation to tightening environmental regulations and targeted R&D into bio-based, high-performance formulations.
Research methodology for baseline estimates
Our research methodology triangulates data from multiple rigorous sources, combining official trade registry statistics, primary stakeholder interviews with chemical engineers, and secondary macroeconomic indicators from global manufacturing indexes to ensure absolute forecast accuracy.
Scope of the report and coverage parameters
This report covers global consumption patterns, pricing dynamics, and technological advancements from 2026 to 2033. Limitations include restricted primary data access within localized state-owned enterprises in emerging economies, mitigated through robust econometric modeling.
Recent developments, product launches, and strategic moves
Recent industry momentum features major joint ventures aimed at chemical recycling of polyurethane foam. Key players have unveiled bio-based thermoplastic grades designed to meet carbon-neutrality targets set by major automotive and appliance manufacturers worldwide.